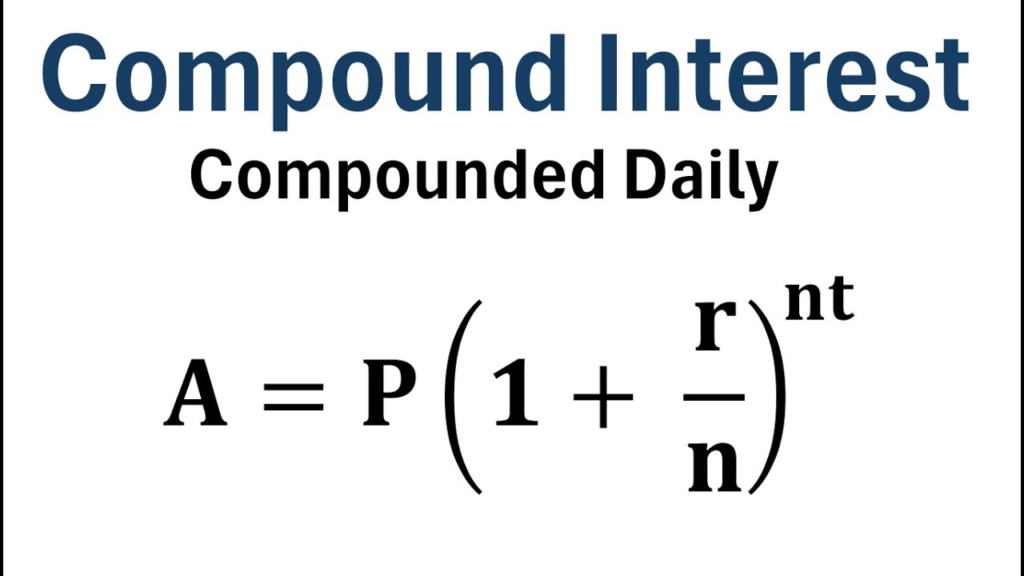

Have you ever wondered how small amounts of money can grow into huge fortunes over time? The secret lies in a powerful financial concept that works behind the scenes in many savings accounts and investments. When you put your hard-earned cash into a bank or investment account, you expect to earn extra money on top of what you deposit. However, the speed at which your money grows depends entirely on how often your earnings are added back to your balance. Understanding how interest accumulates on a daily basis can completely transform the way you save and invest for your future.
Many people leave their money sitting in basic bank accounts without realizing how much earnings they are missing out on. When your financial institution calculates your earnings every twenty-four hours, your money works for you continuously without taking any breaks. This snowball effect helps young savers, busy parents, and retirees reach their long-term financial goals much quicker. In this friendly guide, we will break down everything you need to know about growing your balance every single day in plain and simple terms.
What Is Compound Daily Interest and How Does It Work?
To understand this financial tool, we must first look at how standard interest operates. Simple interest only pays you earnings on the original amount of money you deposited into your account. On the other hand, compound daily interest calculates your percentage returns every single day on both your starting balance and the extra earnings you have already accumulated. This means your total balance grows slightly larger every afternoon, which allows the next day’s earnings to be calculated on a bigger number than the day before.
Imagine planting an apple tree that grows a single seed every night, and that new seed instantly sprouts into another tiny branch the very next morning. By the end of the month, you do not just have one tree; you have a whole orchard producing fruit for you. That is exactly how daily compounding works inside a high-yield savings account or an investment fund. Even if the daily payout seems tiny at first, the continuous cycle creates massive growth over several years.
Why Daily Compounding Beats Monthly and Yearly Interest
The frequency at which your account calculates your returns makes a massive difference over time. Most traditional bank accounts calculate your extra earnings once a month or even once a year. When you earn compound daily interest, your money gets added to your base balance three hundred and sixty-five times every year instead of just twelve times. This rapid pace gives your balance hundreds of extra opportunities to multiply throughout the calendar year.
Let us compare two different savings accounts to see how this plays out in real life. If both accounts offer the exact same annual interest rate, the account that updates your total every day will always end up with more money at the end of the year than the account that updates once a month. The math strictly favors higher frequency because your money gets to work immediately rather than waiting for thirty days to pass. Choosing daily calculations is one of the easiest choices you can make to maximize your wealth.
Simple Daily Compounding vs Other Compounding Types
| Compounding Type | Calculation Frequency | Yearly Growth Speed | Best Account Choice |
| Daily Compounding | 365 Times Per Year | Fastest Growth | High-Yield Savings Accounts |
| Monthly Compounding | 12 Times Per Year | Moderate Growth | Standard Savings & CDs |
| Quarterly Compounding | 4 Times Per Year | Slower Growth | Older Credit Union Accounts |
| Annual Compounding | 1 Time Per Year | Slowest Growth | Traditional Government Bonds |
The Simple Math Behind Compound Daily Interest Calculations
You do not need to be a genius mathematician to figure out how your money grows over time. Financial institutions use a clear formula to figure out your daily return rate. First, they take your annual interest percentage rate and divide it by three hundred and sixty-five days. Then, they multiply that tiny percentage by your total balance at the end of the day. This tiny added amount becomes part of your brand-new balance for the next morning.
Let us look at a quick practical example to make this super clear. If you deposit one thousand dollars into an account that offers compound daily interest, your balance might gain just a few pennies on the first day. On day two, your interest is calculated on your original one thousand dollars plus those few extra pennies from yesterday. By day three hundred, those extra pennies have turned into dollars, which speeds up your overall financial growth significantly without requiring any extra work from you.
Real Life Example: Watching Ten Thousand Dollars Grow
Let us walk through a fun story about two friends named Sarah and Mark. Both friends managed to save ten thousand dollars from their jobs, but they chose completely different bank accounts to hold their money. Mark picked a standard savings account that pays compound interest once a year. Sarah spent time researching her options and placed her money into an online bank account that offers compound daily interest at the exact same overall annual rate.
After five years of leaving their money completely untouched, Sarah checked her bank app and noticed she had significantly more money than Mark. Because Sarah earned compound daily interest, her balance was constantly updating every single afternoon for eighteen hundred days in a row. Mark only had his balance update five total times over those same five years. Sarah was able to use her extra money to take a well-deserved vacation, proving that choosing daily calculations really pays off in the real world.
How Interest Rates Impact Your Daily Growth
The annual percentage yield on your account acts as the primary engine driving your wealth forward. A higher percentage rate means that every single day brings a larger payout into your account balance. Even a tiny fractional increase in your rate can lead to hundreds or thousands of extra dollars over a decade. When you pair a high interest rate with compound daily interest, your money multiplication engine runs at top speed every day.
It is always smart to shop around for the highest available percentage rates before opening a new account. Online banks often offer rates that are much higher than traditional brick and mortar banks because they have lower operating costs. Placing your savings into an account that combines high annual rates with compound daily interest ensures that you earn every single penny you deserve. Keep an eye on market trends so you can always keep your cash parked in the highest-paying accounts available.
The Snowball Effect: How Time Multiplies Your Money
Time is the most important ingredient when you want to build strong financial habits. When you are young, even small deposits can turn into giant piles of cash because time gives the snowball effect room to run. Daily calculations require patience during the first few months because the daily payments look very small on your statement. However, after a few years pass, the daily payouts become larger than your original daily deposits.
Think of time like rolling a tiny snowball down a giant snowy mountain peak. At the very top of the hill, the snowball is so small you can hold it in your hand. As it rolls down the hill, it picks up more snow with every single turn until it becomes a giant boulder at the bottom. That is precisely how compound daily interest works over ten, twenty, or thirty years. Starting as early as possible gives your financial snowball the longest hill to roll down.
Smart Account Types That Offer Daily Compounding
Not every financial account offers the benefit of daily balance calculations, so you must know where to look. High-yield savings accounts provided by modern digital banks are the most popular place to find compound daily interest today. These accounts give you easy access to your money while ensuring your balance keeps growing day and night. Money market accounts at local credit unions also frequently use daily calculation methods to reward their loyal customers.
Another great option to explore is a certificate of deposit that uses daily interest formulas. While these accounts lock your money away for a fixed period of time, they often offer guaranteed returns that compound daily. Before opening any new bank account, take a moment to read the fine print or ask a bank representative how often they calculate interest. Choosing the right account structure from day one will set you up for smooth financial sailing.
Simple Habits to Boost Your Daily Interest Earnings
If you want to squeeze every bit of value out of your bank account, you can adopt a few easy daily habits. First, set up automatic transfers from your checking account so that a portion of your paycheck moves into your savings account immediately. The sooner your cash hits an account offering compound daily interest, the sooner those individual dollars can start working for you. Adding fresh money regularly keeps your compounding engine supplied with fresh fuel.
Another great tip is to avoid taking money out of your savings account unless you face a genuine emergency. Every time you withdraw cash, you shrink the base balance that calculates your compound daily interest every afternoon. Keeping your money safely inside the account allows the continuous multiplication process to run smoothly without interruptions. Try challenging yourself to see how many months you can go without making a single withdrawal from your growing balance.
Common Mistakes That Ruin Your Compounding Progress
One big mistake many beginners make is ignoring sneaky bank fees that eat away at their returns. A monthly maintenance fee of five dollars can completely wipe out all the compound daily interest you earned over thirty days. Always look for fee-free savings accounts so that every penny of interest stays right inside your pocket. Reading account terms carefully prevents hidden costs from ruining your hard-earned progress over time.
Another common pitfall is keeping all your extra money in a standard checking account that pays zero interest. Money sitting in a basic checking account loses buying power every year due to inflation. By moving your emergency fund into an account that pays compound daily interest, you protect your purchasing power and build a safer safety net for your family. Avoiding these simple mistakes ensures your personal money strategy remains strong and effective year after year.
Practical Tools to Track Your Compounding Growth
Tracking your financial progress can be fun and exciting as you watch your total balance grow higher each month. You can find dozens of free financial calculators online that let you type in your starting balance and interest rate. These digital tools will show you exact projections of how compound daily interest will build your wealth over the next five to thirty years. Seeing those future numbers on your screen can give you great motivation to save even more money.
You can also create a simple spreadsheet on your computer to track your monthly balance totals manually. Every time you log into your online banking app, record your updated balance and write down how much interest was added. Seeing your compound daily interest accumulate day after day builds incredible momentum for your financial journey. Knowing your money is making money gives you total peace of mind about your future.
Frequently Asked Questions
Is compound daily interest calculated on weekends?
Yes, banks calculate interest for all three hundred and sixty-five days of the year, including weekends and holidays. Even though banks may be closed on Sunday, your money continues to earn interest behind the scenes.
How often is daily interest actually deposited into my account?
While the interest is calculated every day, most banks batch those daily earnings together and deposit the total into your account once a month. You will see this added amount clearly listed on your monthly statement.
Can I lose money in an account with compound daily interest?
If your money is placed in an insured bank or credit union savings account, your principal balance is completely safe. The daily interest earned is added directly to your guaranteed balance, making it a risk-free way to grow savings.
Does compound daily interest apply to credit card debt?
Yes, daily compounding works in reverse when you owe money on a credit card balance. Credit card companies calculate your interest charges every day, which is why credit card debt can grow out of control very quickly if not paid off.
What is the difference between APY and interest rate?
The interest rate is the basic percentage speed at which your money grows without compounding. The Annual Percentage Yield tells you the total percentage you will actually earn in a full year after taking compound daily interest into account.
How do I start earning compound daily interest today?
You can start immediately by opening a high-yield savings account with an online bank that calculates interest daily. Transfer your savings into the new account, set up recurring deposits, and let the compounding process do the heavy lifting for you.
Conclusion: Start Growing Your Money Today
Building lasting wealth does not require complex trading strategies or risky bets on the stock market. By placing your savings into an account that provides compound daily interest, you allow time and basic math to do the hard work for you. Every single day your cash stays inside the account, it earns fresh returns that build upon yesterday’s progress. Over time, these small daily additions create significant financial stability that can support your biggest dreams.
Take control of your financial future right now by reviewing your current bank accounts. If your money is sitting idle without earning strong daily returns, move it to a high-yield account that works for you twenty-four hours a day. Small actions taken today will compound into major results over the coming years. What is one step you can take today to help your money grow faster?